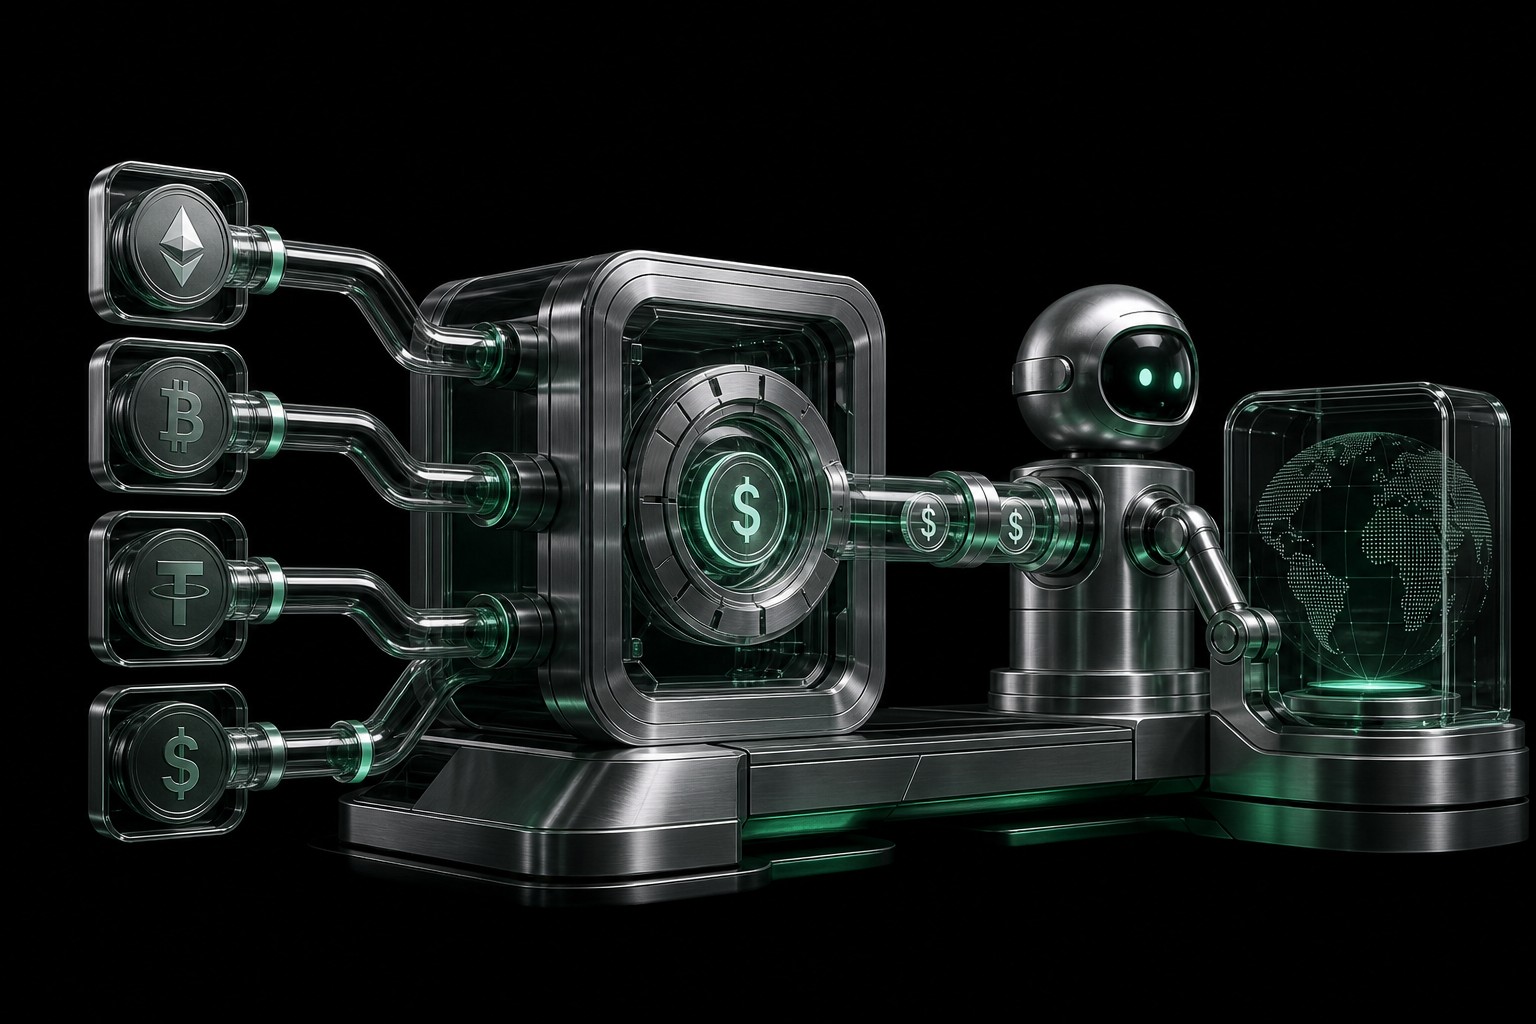
Stablecoins Take Over Payment Rails as Mastercard and Tether Court AI Agents
The “multi-money world” moved from slogan to product this week: Mastercard launched a single API for fiat and stablecoins, Tether backed a platform with 250,000 paying AI agents, and Chainalysis confirmed x402 micropayments surpassed 138 million.
On October 15, Mastercard and BVNK jointly launched the Global Money Platform, putting fiat and stablecoins into the same multi-currency account with real-time conversion, card issuance and cross-border settlement through a single API. It is the first product integration since Mastercard closed its $1.8 billion acquisition of BVNK in August. The same day, Tether Capital announced a strategic investment in AIsa, a platform where more than 250,000 AI agents have processed over 100 million cumulative transactions, letting machines pay per call for APIs, models and data in stablecoins.
A few days earlier, Chainalysis’ 2026 Geography of Crypto report provided hard numbers: as of July, the x402 protocol on Base had processed more than 138 million transactions, 87% of them between $0.0001 and $0.10. The median time from an agent’s first deposit to its first payment collapsed from 73 days in late 2025 to 18 minutes in Q3. Card networks, stablecoin issuers and on-chain data all pointed to the same conclusion in one week: machine payments are no longer an experiment, they are taking over cross-border and high-frequency settlement.
1. Week in Review
· Mastercard Global Money Platform launched: Released October 15, fiat and stablecoin accounts side by side, real-time conversion, stablecoin-linked cards, 17 billion payment endpoints for local settlement through one API; Nuvei and Marqeta among first integrators, expanding to 200+ countries and 40+ currencies in 2027.
· Tether invests in AIsa: October 15, Tether Capital made a strategic investment in AIsa (250K+ AI agents, 100M+ cumulative transactions, 5,000+ API/model catalog), pay-per-call billing with fiat and stablecoin rails; on October 13 it also backed EFY Finance, a Latin American stablecoin settlement firm.
· Chainalysis reports x402 passed 138 million transactions: The 2026 Geography report found 87% of payments were sub-cent micropayments, with median agent activation shrinking to 18 minutes; it also cautioned that high transaction counts do not prove self-sustaining AI demand, since scripts and bots can produce the same pattern.
· EBA classifies USDC as a significant EMT under MiCA: On October 14, the European Banking Authority designated Circle’s French entity-issued USDC as the first “significant EMT” among 45 notified e-money tokens, raising the intensity of supervision.
· Solana Alpenglow upgrade dated: Expected to activate on mainnet in epoch 1064 around October 21, replacing TowerBFT with Votor consensus for roughly 150ms finality (versus about 12.8 seconds today), further cutting latency for machine payments.
· Sui changes CEO, bets on “agentic trust”: Mysten Labs promoted president Kevin Boon to CEO, while co-founder Evan Cheng moves to CTO and leads a new AI unit focused on software that lets AI agents act within limits users set.
· Japan’s big three banks complete yen stablecoin pilot: Mizuho, MUFG and SMBC announced completion of a cross-border yen stablecoin pilot, endorsed by the FSA’s Payment Innovation Project, putting machine payments onto licensed bank ledgers.
2. Top 3 Events of the Week
1. Mastercard moves stablecoins into the mainstream card clearing network. The substance of the Global Money Platform is stitching stablecoin efficiency at the border into local fiat settlement: an enterprise account holds fiat and stablecoins side by side, converts in real time, and uses the balance to pay out to a recipient’s local bank account across Mastercard’s 17 billion endpoints. At the acceptance end, it is still an ordinary card: at settlement the issuer converts the stablecoin into the merchant’s currency and runs it through the card network. Merchants see nothing.
The significance is “who is selling the pipe.” The card network did not issue its own token; it sells access. Banks, fintechs and cross-border businesses no longer need separate vendors for market making, custody, card issuance and clearing. Mastercard calls it infrastructure “not just for stablecoins, but for every form of money,” and explicitly lists agentic commerce and tokenized deposits as the next stage. Competition from Visa and Stripe turns stablecoins from an asset class into a product component of payment giants.
2. Tether shifts from “issuing coins” to “feeding the pipeline.” AIsa is the app store of machine payments: an agent uses one credential to access 5,000+ APIs, models and data, pays per call in fiat or stablecoins, and can set spending caps. 250,000 agents and 100 million cumulative transactions are real machine-side traffic for stablecoins, not a concept. The investment extends Tether’s two-year path from stablecoin issuer to infrastructure investor, from NEURA Robotics to the $400 million Fasanara credit fund, to this week’s EFY Finance.
The signal for practitioners: the stablecoin leader is betting on the execution layer of programmable money. Once machines can buy data and compute on their own, stablecoins stop being just a savings and remittance tool for humans and become operating capital for machines. AIsa’s pay-per-call plus spending caps maps directly to the core questions of the agent economy: who authorizes, how much is spent, and how it is audited.
3. Chainalysis draws a “density map” of machine payments. Of the 138 million transactions, 87% fell between $0.0001 and $0.10, showing that x402’s main battlefield is sub-cent scenarios like per-call API billing, model inference and data access. The behavioral signals matter more: nearly 90% of active wallets re-funded within 30 days, and the median time from first deposit to first payment fell from 73 days to 18 minutes. Agents “activate” far faster than humans.
But the report also cools the hype: on-chain data cannot distinguish agents from scripts and scheduled bots, so surging transaction counts do not prove self-sustaining AI demand. In other words, the density of micropayments proves the machine-payment rail is open, but the loop of “machines earning and spending on their own” is still being validated. That is the data set everyone should watch next week.
3. Trends to Watch
Put the three stories together and a clear evolution line emerges: stablecoins are moving from a “crypto asset” to “general-purpose money infrastructure.”
First, card networks take over the stablecoin “last mile.” Mastercard lets a stablecoin balance become an ordinary card payment at the acceptance end and settle into local bank accounts at the clearing end. It did not overturn the card network; it grafted stablecoin cross-border efficiency onto 17 billion existing endpoints. The implication is that stablecoin adoption is not “replacing existing payments” but “teaching existing payment systems to handle stablecoins.” For banks and PSPs, integration costs are low and the regulatory path is clear, so institutional penetration could come faster than expected.
Second, the division of labor in machine payments is taking shape. x402 handles “how to collect” (HTTP 402 status code plus stablecoin settlement), AIsa provides the paid-service catalog for agents, Mastercard converts stablecoins into local currency, and regulators like the EBA have begun tiering USDC. Every layer has clear players, turning machine payments from scattered experiments into layered infrastructure. Whoever occupies the authorization and audit layer holds the gateway to the agent economy.
Third, regulators are moving to “tiered management” of stablecoins. The EBA’s significant EMT designation means leading stablecoins will face higher-intensity scrutiny while smaller ones get relatively more room. This mirrors the US GENIUS Act’s push to federalize large issuers. Regulatory tiering will accelerate concentration in the stablecoin market and raise the compliance bar for machine-payment rails.
4. Next Week’s Watchlist
· Solana Alpenglow mainnet activation: Epoch 1064 around October 21 switches to Votor consensus; if 150ms finality holds, the latency advantage of machine payments in high-frequency scenarios improves further.
· EBA significant EMT rules: How USDC’s post-designation obligations (reserves, audits, disclosures) land, and whether other stablecoins copy the designation, will set the tone for the European stablecoin market.
· First Mastercard Global Money Platform customers go live: The integration progress of Nuvei and Marqeta and the first stablecoin card and clearing use cases will test whether the “multi-money world” is a product or a press release.
· Progress on US agent identity standards: After Amazon blocked Meta’s Muse and JPMorgan rejected external agents, whether identity protocols like Proof’s x401 become an industry standard will define the trust foundation of the agent economy.
- Mastercard — Mastercard and BVNK Launch Global Money Platform
- Crypto Briefing — Tether Invests in AIsa to Enable Stablecoin Payments for AI Agents
- Tether — Tether Invests in AIsa (2026-10-15)
- CoinAlert — AI Adoption Surges in Crypto Trading and Payments
- Finobird — Crypto News Roundup 2026-10-17
- MEXC — Latest Crypto News (EBA significant EMT)
- Crypto Watch Desk — Chain Check 17 Oct
- Fintech Garden — Mastercard Rolls Out Global Money Platform
发表回复