作者: MzaZobV4JT53byg

  • 稳定币的”银行化”分叉:台湾双重审批锁死发行权,马来西亚首发银行美元稳定币

    稳定币的”银行化”分叉:台湾双重审批锁死发行权,马来西亚首发银行美元稳定币

    稳定币的”银行化”分叉:台湾双重审批锁死发行权,马来西亚首发银行美元稳定币

    全球稳定币市值突破 3000 亿美元之际,亚洲同一周给出两条截然不同的答案。台湾用”央行+金管会”双重审批把发行权锁进银行体系,马来西亚持牌数字银行直接把 1:1 储备放进自家资产负债表,让赎回从”储备管理人的承诺”变成”银行负债”。

    文章解读

    台湾 6 月三读通过的《虚拟资产服务法》把稳定币发行权锁进银行体系:发行须同时取得央行同意与金管会许可,储备放入信托专户、定期审计、禁止付息,法配套最快 2027 年第一季完备。同一周,马来西亚持牌数字银行 Monfi 推出 MUSD,把 1:1 美元储备放进银行自身资产负债表的隔离账户,赎回成为银行义务,底层由 Tether 的 Hadron 与 Estable 技术驱动。两条路径殊途同归:稳定币正从”非银行储备池”走向”银行资产负债表”,而”谁对 1:1 承诺负责”成为亚洲监管与市场的共同追问。

    台湾 VASA:双重审批把稳定币留给银行

    台湾《虚拟资产服务法》(VASA)6 月 30 日在立法院三读通过、7 月 22 日公布,共 56 条,将虚拟资产监管从”反洗钱登记”全面升级为”事前许可牌照制”。针对稳定币,法案设计了一套在亚洲区域中门槛最高的机制:发行方需同时取得台湾中央银行同意与金融监督管理委员会(金管会)许可,两者缺一不可,这是比单一机构牌照更严格的双监管审批门。

    储备要求同样严苛:发行方须将 100% 等值储备放于岛内金融机构的信托专户,与发行人自身资产隔离、不受破产波及,并接受定期独立审计与披露。法案同时明文禁止向持有人支付利息或收益。在收益分配上,台湾与新加坡 MAS 的”稳定币禁息”立场一致,而与美国 GENIUS 法案下”储备收益归发行人”的默认结构形成对照。

    最具结构性的一点是发行主体的准入门槛:金管会与央行已初步达成共识,上线初期只允许金融机构(即银行)发行稳定币,非银机构须待后续阶段再行开放。这意味着台湾的首批稳定币发行者不会是加密原生公司,而是受银行法约束、已有资本充足率与存款保险框架的传统银行。此前金管会已推动四家银行参与虚拟资产托管试点,为银行进入数字资产业务积累基础。

    “稳定币制度不仅涉及子法订定,还需完成母法及相关法制作业……金管会希望在 2027 年第一季完成法规配套,目标是 3 月底以前完备,但实际生效时间仍须配合法定程序。”
    — 金管会主委 彭金隆,中评网专访,2026 年 10 月

    罚则方面,未经许可经营虚拟资产业务的最高刑责从此前反洗钱法登记制下的 2 年有期徒刑、500 万元新台币罚款,大幅提升至 7 年有期徒刑、1 亿元新台币罚款。既有 AML 注册平台享有 12 个月宽限期申请牌照,最长 21 个月内须完成全面金管会批准。VASA 及其九部子法须同步生效,金管会此前表态最快 2027 年第一季,彭金隆则把目标锁定在 3 月底前完备法配套。这意味着在生效之前,台湾市场没有任何稳定币可合法发行。

    Monfi MUSD:把储备放进银行资产负债表

    10 月 19 日,总部位于马来西亚的持牌国际数字银行 Monfi Digital Bank 宣布推出 Monfi USD(MUSD),成为全球首批由持牌银行直接发行的美元稳定币之一。与绝大多数由非银实体发行、储备托管于第三方机构的稳定币不同,MUSD 的 1:1 美元储备存放在 Monfi 银行自身资产负债表的专用隔离账户中,与营运资本、监管资本及其他客户存款严格分离。

    MUSD 的储备仅由美元现金及现金等价物构成,不杠杆、不出借、不进行再抵押(rehypothecation),逐日与流通量对账、按季度公布、并接受年度独立第三方验证。持有人的兑付权利直接指向一家持牌银行,赎回是银行义务,而非储备管理人的单方承诺。发行结构上,MUSD 由 Estable 与 Tether 的 Hadron 平台提供技术支持,Fireblocks 负责托管基础设施与密钥管理,Chainalysis 提供链上监控与制裁筛查。面向跨境支付、贸易结算、财资管理与代币化资产结算等场景,现供完成 KYC/KYB 的机构与合格私人客户使用。

    维度 台湾 VASA Monfi MUSD
    监管结构 央行同意 + 金管会许可(双监管门) 持牌数字银行直接发行,受同一银行监管者约束
    储备存放 岛内金融机构信托专户,100% 隔离 银行自身资产负债表的隔离账户
    收益分配 禁止付息或收益 未公开收益设计,储备不出借不杠杆
    兑付义务 按面值赎回,细则待子法 按面值赎回,属银行义务
    生效时间 法配套目标 2027 年第一季完备,VASA 与九部子法同步生效 2026 年 10 月 19 日已上线

    把两条路径放到同一坐标轴上看,台湾与 Monfi 分别代表了”监管约束发行”与”市场自选结构”两种银行化路线。台湾版本把稳定币定义为需要双监管审批的金融产品,用牌照准入把发行权留给银行,把”谁可发行”从市场博弈变成政策决定;Monfi 版本则用银行资产负债表本身作为信任来源,把”谁对储备负责”写进产品结构。两者都没有把稳定币当作独立于银行体系之外的”影子货币”,而是明确地把 1:1 承诺挂在受监管机构的资产负债表上,分歧只在于由谁、以何种方式背书。

    对从业者的一些启示

    1
    银行资产负债表正在成为稳定币的默认信任载体
    台湾把发行权锁进银行,Monfi 把储备放进银行账本,方向一致:1:1 承诺的最终责任方正在从”储备管理人”迁移到”受监管金融机构”。对从业者而言,持有稳定币时评估的不再只是发行商的资产质量,还包括其所在司法管辖区的银行监管与破产隔离制度——同样的美元稳定币,在银行资产负债表上和在第三方托管储备池里,风险结构并不相同。

    2
    “禁息”正在成为亚洲稳定币监管的默认项
    台湾 VASA 明文禁止向持有人付息,与新加坡 MAS 的”稳定币禁息”要求一致。当主要亚洲经济体都把”付息稳定币”排除在监管框架之外,机构若计划在亚洲展业,产品设计需要从一开始就放弃收益型稳定币路线,把合规重点放在储备透明度、赎回机制与流动性安排上。

    3
    银行主导的发行结构会改变渠道与话语权
    台湾初期只允许银行发行稳定币,意味着渠道、托管、结算都将围绕银行体系展开,加密原生平台的角色被压缩为分发与流通环节。这与美国 GENIUS 法案下 OCC 特许信托银行路径、欧盟 MiCA 下电子货币机构路径一起,构成了全球稳定币发行权的三种制度模板。非银机构若想保留发行能力,需要尽早寻找银行合作伙伴或取得电子货币机构牌照。

    4
    “谁对 1:1 负责”将成为下一轮机构尽调的核心问题
    MUSD 把赎回定义为银行义务,Circle 等发行商把赎回定义为发行人承诺,台湾则把赎回细则留给子法。三种表述对应三种不同的法律追索路径。机构买家在配置美元稳定币时,应当把”兑付义务的法律性质”作为尽调必选项,区分银行负债、发行人负债与信托保障之间的差异,而不是只看市值排名与审计报告。

    5
    亚洲市场进入”规则竞速”阶段,时间窗口有限
    台湾目标 2027 年第一季完备法配套,新加坡已关闭稳定币咨询、香港已发出首批发行人牌照,马来西亚出现银行发行先例。亚洲主要经济体正在同一季度内密集落地稳定币制度。对跨境从业者而言,制度窗口期正在快速收窄:先落地的司法管辖区会吸引存量业务迁移,而后落地的市场将面对更高的合规套利成本。现在就需要根据各辖区生效日期倒排合规计划。

  • 存款代币登上以太坊,华尔街把现金接入链上结算

    存款代币登上以太坊,华尔街把现金接入链上结算

    A
    Aurellix
    2026年10月20日
    1 分钟阅读

    今日焦点
    摩根大通将 JPM Coin 扩展至以太坊主网,机构存款首次进入公链结算,RWA 的「现金腿」补齐。代币化美债赛道上 Ondo USDY 反超 BUIDL 登顶,市场总规模逼近 $150 亿;DTCC 代币化服务十月商业化上线,$114 万亿托管资产 0.5% 上链即新增 $5700 亿。

    行业速报

    共 10 条

  • JPM Coin 扩展至以太坊主网 — 摩根大通将美元存款代币 JPMD 从 Base 扩展至以太坊 L1,机构 24/7 近乎实时转账,存款现金首次登上公共区块链
  • Ondo USDY 反超 BUIDL 登顶 — $23.28 亿 vs $22.04 亿,Ondo 平台合计破 $30 亿居首,Circle USYC $23.8 亿仍是最大单产品
  • DTCC 代币化服务商业化上线 — 贝莱德、高盛、摩根大通等 25+ 机构在产线运行,$114 万亿托管证券可在 DTC 营业时间外 24/7 转移
  • 贝莱德推代币化基金作抵押品 — 亚太现金业务主管 Dan Maley 称 BUIDL 已用作数字资产抵押,IMF 与 ISDA 指碎片化、法律不确定性仍是障碍
  • SIFMA 敦促 SEC 厘清豁免细则 — 就创新豁免提出发行人通知、交易量上限、受益所有权四大问题,多个 TSV 或将在 30 天内开始运营
  • SEC 加密规则评论今日截止 — Hyperliquid 与 KoreInside 提交意见信,空投定性、二级交易与回购自动化成核心争议点
  • TRON 进军代币化股票与美债 — Justin Sun 称 Q4 2026 首发代币化股票,目标亚洲与新兴市场,预测五年内代币化股票市场超 $1000 亿
  • Solana RWA 达 $43.8 亿 — 30 天转账量 $87.3 亿环比 +39.56%,持有者 92.4 万 +43.56%,Ondo 与 xStocks 累计 DEX 交易额 $27.6 亿
  • De¹ 上线 BNB Chain 代币化资产世界 — 首个金融世界模型垂直域,整合 PancakeSwap、ListaDAO 等信号训练 AI 代理理解 RWA 全链路
  • 代币化美债周增 $7580 万 — Ondo 一周新增 $4160 万、Superstate $3420 万领跑,总规模 $149-155 亿,但 DeFi 使用率仍仅 0.4%-2%
  • Deposit Tokens Hit Ethereum as Wall Street Brings Cash Onchain for Settlement

    Deposit Tokens Hit Ethereum as Wall Street Brings Cash Onchain for Settlement

    A
    Aurellix
    October 20, 2026
    1 min read

    Today’s Focus
    JPMorgan is taking JPM Coin to Ethereum mainnet, putting institutional deposits on a public chain for the first time and filling in the cash leg for RWA settlement. In tokenized Treasuries, Ondo’s USDY overtakes BUIDL for the top spot as the market nears $15 billion; DTCC’s tokenization service goes live commercially, with $114 trillion in custody — just 0.5% onchain adding $570 billion.

    Industry Flash

    10 items

  • JPM Coin Expands to Ethereum Mainnet — JPMorgan is taking its dollar deposit token JPMD from Base to Ethereum L1 for near-real-time 24/7 institutional transfers, putting deposit cash on a public blockchain for the first time
  • Ondo USDY Overtakes BUIDL at the Top — $2.328B vs $2.204B, with Ondo’s platforms topping $3B combined; Circle’s USYC at $2.38B remains the largest single product
  • DTCC Tokenization Service Goes Live — BlackRock, Goldman Sachs, JPMorgan and 25+ firms run in production, letting $114 trillion of custodied securities move 24/7 outside DTC operating hours
  • BlackRock Pushes Tokenized Funds as Collateral — APAC cash chief Dan Maley says BUIDL already serves as digital-asset collateral, while IMF and ISDA flag fragmentation and legal uncertainty as hurdles
  • SIFMA Urges SEC to Clarify Exemption Rules — comments on issuer notice, volume caps and beneficial ownership ahead of tokenized securities venues that could launch within 30 days
  • SEC Crypto Rule Comments Close Today — Hyperliquid and KoreInside file letters, with airdrop classification, secondary trading and automated buybacks as the core flashpoints
  • TRON Moves Into Tokenized Stocks and Treasuries — Justin Sun targets a Q4 2026 tokenized share launch for Asia and emerging markets, projecting a $100B+ market within five years
  • Solana RWA Hits $4.38B — 30-day transfer volume of $8.73B is up 39.56% with 924K holders (+43.56%); Ondo and xStocks post $2.76B in cumulative DEX volume
  • De¹ Launches Tokenized Asset World on BNB Chain — the first vertical of its Financial World Model trains AI agents on PancakeSwap and ListaDAO signals to grasp the full RWA stack
  • Tokenized Treasuries Add $75.8M in a Week — Ondo gains $41.6M and Superstate $34.2M to lead, with the market at $14.9-15.5B but DeFi usage still only 0.4%-2%
  • Deposit Tokens Hit Ethereum as Wall Street Wires Cash Into Onchain Settlement

    Deposit Tokens Hit Ethereum as Wall Street Wires Cash Into Onchain Settlement

    Deposit Tokens Hit Ethereum as Wall Street Wires Cash Into Onchain Settlement

    Tokenized RWA Market
    $38.8B
    The Block · Oct 2026

    DTC Custody Assets
    $114T
    0.5% onchain = $570B

    BUIDL Fund Size
    $2.3B
    BlackRock MMF

    SEC Crypto Rules Comment
    10/20
    Deadline today

    JPMorgan Brings JPM Coin to Ethereum Mainnet as Institutional Deposits Enter Public Chains

    October 19, 2026 · Bloomberg / crypto.news
    JPMorgan on Monday said it is extending JPM Coin (ticker JPMD), its token representing US dollar deposits, to the Ethereum mainnet, giving approved institutional clients around-the-clock, near-real-time fund transfers and settlement. The move marks a pivotal shift in Wall Street’s asset-tokenization trajectory — from “putting securities onchain” to “bringing deposit cash onto the same network” to back tokenized-securities trading with settlement liquidity and collateral.
    • JPMD debuted on Coinbase’s Base layer-2 in November 2025; this Ethereum L1 expansion continues the path “from private networks to public infrastructure”
    • Ethereum offers mature onchain liquidity and a deep tokenized-asset ecosystem, letting institutions move assets and settlement cash on the same chain without cross-chain coordination
    • Access stays restricted to approved institutions and vetted counterparties — not retail — with payments, securities settlement and collateral transfers as the three core use cases
    • Operated by the Kinexys business (formerly Onyx); JPMD is a deposit claim on JPMorgan, structurally distinct from nonbank stablecoins
    • The bank also plans phased JPMD integration with the Canton Network during 2026, cementing a multi-chain distribution strategy
    Structural Significance
    The largest US bank’s deposits now sit on a public blockchain, completing the “cash leg” of institutional settlement and enabling onchain DvP

    Industry Signal
    From permissioned ledgers to public chains, Wall Street’s tolerance for shared infrastructure is materially loosening

    Boundary
    Permissioned access caps free circulation on the public chain, keeping JPMD and stablecoins on separate compliance and liquidity tracks

    Source: crypto.news · ETHNews · October 19, 2026

    BlackRock Pushes Tokenized Funds Into Collateral as IMF and ISDA List Adoption Hurdles

    October 19, 2026 · Bloomberg / CLS
    Dan Maley, who oversees BlackRock’s cash business in Asia Pacific, said its tokenized funds are already being used as collateral in the digital-asset market, and the firm is trying to extend that use into traditional finance. The core logic: tokenization does not change what a money-market fund owns — it changes the rails on which ownership moves, letting shares transfer 24/7 without first redeeming for cash. Both the IMF and ISDA, however, flag platform fragmentation, legal uncertainty and weak links to legacy infrastructure as key barriers.
    • BUIDL has grown to roughly $2.3 billion since its 2024 launch, one of the largest products of its kind; tokenized cash products are live in the US and Europe, and a Hong Kong-dollar digital liquidity fund was approved in September
    • Early users are largely crypto-native investors holding stablecoins onchain and seeking yield; “the extension into collateral was also from that cohort”
    • ISDA CEO Scott O’Malia: custody and segregation frameworks, capital and margin treatment, cross-border recognition and legal certainty must be addressed with industry standards and regulatory clarity
    • Traditional money-market funds already serve as collateral for initial and variation margin; tokenization lets institutions move exposure without redeeming first, keeping assets invested longer
    • Maley stresses that fund tokens can change hands 24/7, but that “does not necessarily mean investors can redeem them for cash at any hour” — liquidity and redemption are different
    Use-Case Shift
    From issuance and holding into margin and collateral management, tokenization enters the daily core of market operations

    Core Barriers
    Institutional acceptance, infrastructure compatibility and regulatory certainty decide whether crypto use cases spill into TradFi

    Key Distinction
    “24/7 transfer” is not “24/7 redemption” — the value sits in ownership movement, not liquidity promises

    Source: CLS · Bloomberg via KleverStock · October 19, 2026

    SIFMA Urges SEC to Resolve Innovation Exemption Questions Before Tokenized Venues Launch

    October 19, 2026 · SIFMA press release
    SIFMA submitted a comment letter to the SEC on the Commission’s recently published Innovation Exemption, setting out an initial set of questions and recommendations on how the order will work in practice. Because the exemption took effect the moment it was published, issuers, investors and intermediaries had no chance to comment on its structure, while multiple Tokenized Securities Venues (TSVs) have already published notices and may begin operating within 30 days.
    • Four focus areas: issuer notice and consent (including control), investor protection and illicit-finance oversight, trading volume limits (per-venue and in aggregate), and beneficial ownership / corporate actions / transferability
    • Recommends clarifying operations via FAQs or guidance; some fixes would require amending the order, such as affirmative issuer consent, a longer objection period and a universal issuer opt-out
    • Because the relief lasts five years, early design choices will shape market practice well before any permanent framework is adopted
    • SIFMA welcomes Chairman Atkins’ and Commissioner Uyeda’s statements that formal notice-and-comment rulemaking will follow
    • Echoes the nine issuers’ objections to OKXICE: the divergence between issuers’ and tokenizers’ interests is becoming the exemption’s main friction point
    Window Battle
    Immediate-effect exemption plus a 30-day objection window pushes the industry to demand a “comment before operating” fix

    Issuer Rights
    Calls to move from implied consent to affirmative consent could reshape which stocks TSVs can cover

    Five-Year Stakes
    Early design choices will harden market practice; exemption-period experience will determine the permanent framework

    Source: SIFMA · October 19, 2026

    SEC Crypto-Asset Rule Comments Close Today as Industry Debates Airdrops, Secondary Trading and Buybacks

    October 19, 2026 · crypto.news / Morningstar
    The public comment window for the SEC’s Regulation Crypto Assets framework, proposed in August, closes today (October 20). Hyperliquid Policy Center and KoreInside both filed comment letters before the deadline, weighing in on airdrop treatment, secondary trading, automated buybacks and investor protections. The framework would create registration exemptions for qualifying crypto projects — a startup exemption for up to $5 million raised over four years, and a separate fundraising exemption for up to $75 million within 12 months.
    • Hyperliquid’s policy center proposes five changes: codify the existing interpretation that free distributions without payment do not satisfy the investment-of-money test; clarify secondary trading after exempt offerings; distinguish automated token repurchases from operator-directed buybacks; developer protections; and state securities registration requirements
    • KoreInside lists six operational priorities: durable disclosure archives, reusable identity credentials, clear ownership and settlement responsibilities, technology-neutral implementation (public/permissioned/hybrid ledgers), evidence-backed regulatory transitions, and compatible data export standards
    • Airdrop treatment is the sharpest divide: Hyperliquid argues routine delivery steps like wallet connections and sanctions screening should not automatically turn a free distribution into a securities transaction
    • The SEC’s own economic analysis acknowledges that limited secondary-market liquidity could reduce the expected benefits of the exemptions, leaving the framework torn between capital formation and investor protection
    • The SEC and CFTC issued joint crypto classification guidance in March covering airdrops and staking
    Rule Trajectory
    Comments closing today will directly shape the final rule, with airdrop and secondary-trading terms as the core battleground

    Innovation vs Protection
    A $5M/$75M dual-exemption path, if finalized, would redraw the US crypto primary-market map

    Industry Shift
    Protocols like Hyperliquid are systematically engaging US rulemaking for the first time — the dialogue moves from confrontation to participation

    Source: crypto.news · Morningstar · October 19, 2026

  • RWA 早报 | 2026年10月20日

    RWA 早报 | 2026年10月20日

    存款代币登上以太坊,华尔街把现金接入链上结算

    代币化 RWA 总市值
    $388亿
    The Block · 10月

    DTC 托管资产
    $114万亿
    0.5% 上链 = $5700 亿

    BUIDL 规模
    $23亿
    贝莱德代币化货币基金

    SEC 加密资产规则评论
    10/20
    今日截止

    摩根大通将 JPM Coin 扩展至以太坊主网,机构存款首次进入公链结算

    2026年10月19日 · Bloomberg / crypto.news
    摩根大通周一宣布,将代表美元存款的代币 JPM Coin(代码 JPMD)扩展至以太坊主网,为其机构客户提供 24/7、近乎实时的资金转移与结算能力。这是华尔街资产代币化轨迹的关键转折——从「把证券搬上链」推进到「让存款现金也进入同一张网络」,为代币化证券交易提供结算资金与抵押品划转支撑。
    • JPMD 于 2025 年 11 月率先登陆 Coinbase 的 Base 二层网络完成试点,本次扩展至以太坊 L1,属「从私有网络走向公共基础设施」的延续
    • 以太坊拥有成熟的链上流动性与代币化资产生态,机构可在资产与结算现金同链流转,无需跨链协调
    • 参与仍限获准机构及审核交易对手,不面向零售;用途聚焦支付、证券结算与抵押品划转三大场景
    • Kinexys 业务线(原 Onyx)负责运营;JPMD 代表对摩根大通的存款债权,与稳定币有本质区别
    • 银行还计划 2026 年分阶段将 JPMD 接入 Canton Network,多链分发策略成型
    结构性意义
    最大美资银行的存款首次出现在公共区块链,机构结算的「现金腿」补齐,链上 DvP 成为可能

    行业信号
    从私有许可链到公链,华尔街对公共基础设施的接受度出现实质性松动

    边界约束
    许可制访问限制了公链上的自由流动,JPMD 与稳定币在合规与流通性上分道而行

    来源:crypto.news · ETHNews · 2026年10月19日

    贝莱德推动代币化基金进入抵押品场景,IMF 与 ISDA 列出融入障碍清单

    2026年10月19日 · Bloomberg / 财联社
    贝莱德亚太区现金业务负责人 Dan Maley 表示,其代币化基金已作为数字资产市场的抵押品使用,公司正试图将这一用途延伸至传统金融体系。核心逻辑是:代币化不改变货币基金持有的资产,只改变所有权流转的底层通道——基金份额可 24/7 转移而无需先赎回为现金。但 IMF 与 ISDA 均指出,平台碎片化、法律不确定性与传统基础设施衔接仍是关键障碍。
    • BUIDL 自 2024 年推出以来已增长至约 $23 亿,是同类产品中规模最大的之一;美欧均已推出代币化现金产品,9 月获批港元数字流动性基金
    • 首批用户多为链上持有稳定币、寻求收益的投资者,「向抵押品延伸也来自这一群体」
    • ISDA CEO Scott O’Malia:托管与隔离框架、资本与保证金处理、跨境认可及法律确定性,必须通过行业标准和监管明确性解决
    • 传统货币市场基金已用于初始与变动保证金;代币化可让机构转移持仓而无需先赎回,保持资产持续投资
    • Maley 强调基金代币可全天候易手,但「不代表投资者能在任何时间赎回为现金」——流动性与赎回是两回事
    应用跃迁
    从发行与持有延伸至保证金与抵押品管理,代币化进入金融市场日常运转核心环节

    核心障碍
    机构接受度、基础设施兼容与监管确定性三大门槛,决定加密用例能否外溢至 TradFi

    关键区分
    「全天候转移」≠「全天候赎回」,代币化的价值在所有权流转而非流动性承诺

    来源:金融界 · Bloomberg via KleverStock · 2026年10月19日

    SIFMA 敦促 SEC 厘清创新豁免细则,代币化交易场所上线前四大悬而未决

    2026年10月19日 · SIFMA 新闻稿
    美国证券业与金融市场协会(SIFMA)向 SEC 提交评论信,就 9 月发布的「创新豁免」提出首批操作性问题与建议。由于豁免自发布即生效,发行人、投资者与中介机构没有机会就其结构发表意见,而多个代币化证券交易场所(TSV)已发布通知、可能在未来 30 天内开始运营,SIFMA 敦促委员会尽快解决四大焦点问题。
    • 四大焦点:发行人通知与同意机制(含控制权)、投资者保护与反洗钱/监管执行、交易量上限的适用(单场所与跨市场合计)、受益所有权/公司行动/可转让性
    • 建议通过 FAQ 或指引明确操作方式;部分建议需修订豁免令,如要求肯定式发行人同意、延长异议期、建立统一发行人退出机制
    • 因豁免为期五年,早期设计选择将塑造市场实践,远早于永久框架落地
    • SIFMA 认可 Atkins 与 Uyeda 关于正式 notice-and-comment 规则制定的表态,愿参与后续评估
    • 呼应 9 家发行人对 OKXICE 的反对潮:发行人与代币化平台利益分歧正成为豁免落地的主要摩擦点
    窗口期博弈
    豁免即时生效 + 30 天异议窗口,行业组织要求补上「先评论后运营」的制度缺口

    发行人权利
    从「默示同意」走向「肯定式同意」的呼声,或改变 TSV 未来股票覆盖结构

    五年影响
    早期设计选择将固化市场实践,豁免期内的经验将直接决定永久框架形态

    来源:SIFMA · 2026年10月19日

    SEC 加密资产规则评论今日截止,业界围绕空投、二级交易与回购激辩

    2026年10月19日 · crypto.news / Morningstar
    SEC 于 8 月提出的 Regulation Crypto Assets 框架公众评论窗口将于今日(10 月 20 日)截止。Hyperliquid Policy Center 与 KoreInside 均在截止前提交评论信,围绕空投定性、二级交易、回购自动化与投资者保护等议题提出建议。这一框架拟为符合条件的加密项目提供注册豁免——初创豁免四年内最高融资 $500 万,另一通道 12 个月内最高 $7500 万。
    • Hyperliquid 政策中心提出五项建议:将空投「未支付对价即不构成投资合同」的既有解释写入规则;明确豁免发行后的二级交易流转;区分自动化回购与中心化操作者主导回购;开发者保护;州证券注册要求
    • KoreInside 提出六项运营优先项:持久化披露档案、可复用身份凭证、所有权与结算责任界定、技术中立(公链/许可链/混合链)、监管过渡证据、数据导出兼容标准
    • 空投定性是最大分歧点:Hyperliquid 认为钱包连接与制裁筛查等例行交付程序不应自动构成证券交易
    • SEC 自身经济分析已承认有限二级流动性可能降低豁免预期收益,框架在「融资便捷」与「投资者保护」间摇摆
    • SEC 与 CFTC 今年 3 月曾联合发布加密分类指引,覆盖空投、质押等领域
    规则走向
    今日截止的评论将直接塑造最终规则形态,空投与二级交易条款是核心争议点

    创新与保护
    $500 万/$7500 万双豁免通道若成行,将重划美国加密一级市场版图

    行业预期
    Hyperliquid 等协议首次系统参与美国规则制定,监管对话从「对抗」转向「参与」

    来源:crypto.news · Morningstar · 2026年10月19日

  • USDC Dominates AI-Agent Payments as x402 V2 Reaches Banking Rails

    USDC Dominates AI-Agent Payments as x402 V2 Reaches Banking Rails

    USDC Dominates AI-Agent Payments as x402 V2 Reaches Banking Rails

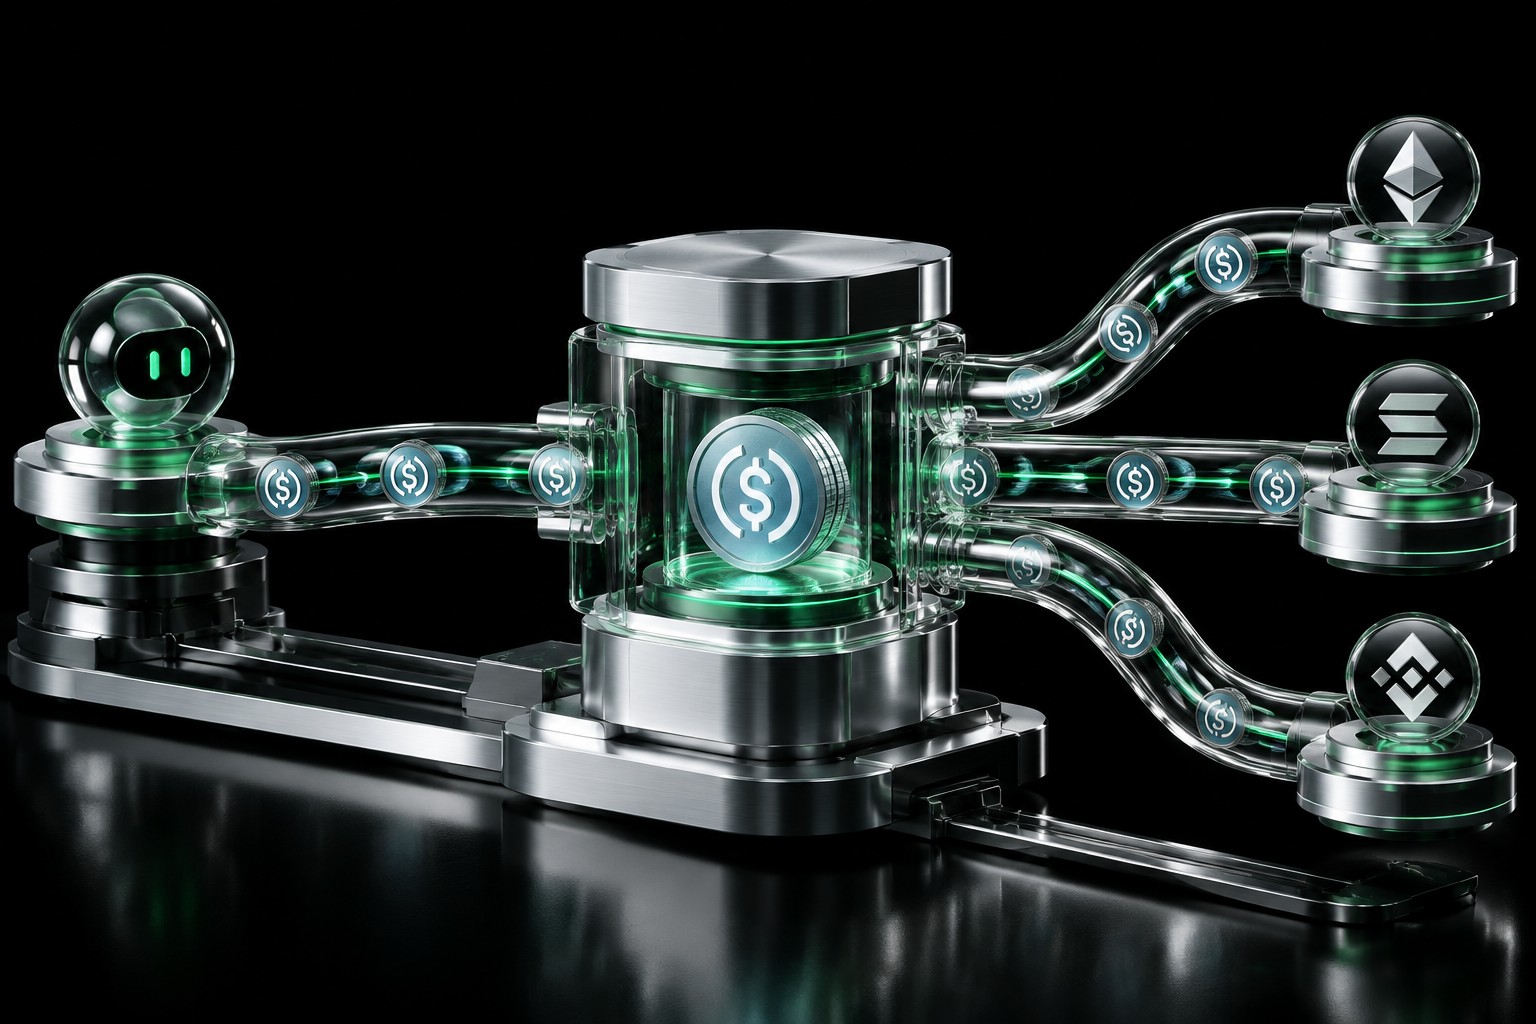
    Chainalysis counts 138M+ x402 settlements on Base in a year, USDC has become the default payment rail for AI agents, and Coinbase and Circle are pushing machine payments onto cross-chain and institutional settlement layers at the same time.

    x402 annual transactions
    138M+
    On Base network

    USDC circulating supply
    $70-80B
    14-16x the MiCA threshold

    AI inference payments from US
    88.1%
    Wallet geolocation

    Median time to first agent payment
    73d → 18min
    A one-year transformation

    This week the infrastructure battle over machine payments entered a new phase. Chainalysis latest annual report shows AI agents have processed more than 138 million transactions through the x402 protocol on Coinbase Base network in a year, while Token Terminal 30-day data confirms USDC as the stablecoin AI agents use most often for settlement. At the same time, Coinbase released x402 V2 on October 11, using a unified interface to connect Base, Solana and traditional banking networks such as ACH; Circle keeps stacking AI-native capabilities onto Arc, its institutional-grade Layer 1 blockchain, with CEO Jeremy Allaire publicly predicting that AI agents will become Arc primary users.

    Three events look independent but point to the same conclusion: machine payments are switching from a token-issuance narrative to a settlement-rail one, and American companies are seizing the high ground at both the cross-chain protocol layer and the institutional settlement layer.

    1. 138 Million Micropayments: A Density Signal, Not a Scale Signal

    In its 2026 Geography report, Chainalysis counts more than 138 million x402 payments made by AI agents on Base in the 12 months through July 1, 2026. That compares with roughly 1,500 transactions in Q2 2025, a jump of about 90,000x. More than 87% of the payments fall between $0.0001 and $0.10, with the most common range from one to ten cents.

    Micropayments are reshaping the timescales of wallet behavior. At the end of 2025, the median time from a wallet first funding to its first spend was 73 days; by Q3 2026 that had collapsed to 18 minutes. Only 4% of wallets spent within an hour of funding a year ago; that share now stands at 67%, and 89.3% of wallets are reloaded within 30 days of first funding.

    Where the money goes is just as telling: agents buy model inference, tool catalogs, data and research APIs, and code auditing, in other words, robots purchasing AI-generated knowledge on the blockchain. Chainalysis notes that transactions below a dollar make no economic sense for a credit-card network, while a stablecoin that settles for less than a cent fits the scenario naturally.

    Key signal: Surging transaction counts are not a scale signal, they are a density signal. Most of the 138M transactions are cent-level micropayments with limited cumulative value. But wallet activation time dropping from 73 days to 18 minutes, and same-hour spending rising from 4% to 67%, show agent wallets are no longer test demos but working with real tasks.

    2. The US Leads AI Payments: A Geographic Divide of AI Nationalism

    Chainalysis draws a striking split among geolocatable agent payments. US wallets carry 88.1% of AI model inference payments, 41.8% of payments to agent frameworks and tool catalogs, and 23.2% of data and research API purchases, meaning the brain, hands and raw materials of agentic software are paid for mainly from the United States. Chinese wallets account for nine in ten security and code analysis transactions, almost all flowing to AgentLISA, a service that audits Solidity smart contracts with a language model, while also covering 46.7% of financial intelligence and 35% of payment-rail spending.

    Chainalysis explains the split as AI nationalism: DeepSeek and Qwen are free in open weights, while ChatGPT and Claude charge per request, so the market for machine-purchased intelligence concentrates where it costs something. The US ranks first with about 30% of all geolocatable agent-to-service transactions, a number that further confirms the geographic shape of machine payments at the AI infrastructure level.

    Regulatory implications follow. Chainalysis warns that payments that are too fast, too small and too numerous cannot serve as a control point, so responsibility must fall on whoever deployed and funded the agent, not the agent itself. Cloudflare opened capped dedicated wallets for agents in August, while Circle reported USDC circulating supply of $73.3 billion at end of September, up 19% year over year, with $14.8 trillion settled on-chain in a single quarter.

    3. x402 V2: One Format Across Chains, Machine Settlement Straight to Banks

    On October 11, Coinbase released x402 V2 on its developer platform. The core of V1 was reviving the dormant HTTP 402 status code so agents could settle stablecoin micropayments directly over HTTP. The breakthrough of V2 is hybrid compatibility: a unified interface supports both high-performance blockchains such as Base and Solana and traditional banking networks such as ACH and automatic debits, so developers no longer write extra logic for each payment rail.

    The new payTo dynamic-routing feature lets companies set billing rules as intuitively as dragging a web component, and in the future paywalls will no longer stop humans but let machines complete handshakes and checkouts behind each other backs. x402 had already processed more than 100 million transactions in the prior six months; V2 upgrades that into a single payment format that runs cross-chain and is compatible with traditional payment channels. Coinbase works closely with Cloudflare and Circle, using USDC and cryptographic signatures to compress settlement to the millisecond level.

    The move tracks with the x402 Foundation expansion. On September 23, the Foundation merged a spec for exact payments over the Bitcoin Lightning network, with Block contributing the scheme, letting agents pay x402 endpoints in bitcoin via BOLT11 invoices. The x402 rail is extending from a single EVM scope into a general machine-payment protocol covering multiple chains, fiat and bitcoin.

    4. Circle Arc: An AI-Native Design for the Institutional Settlement Layer

    Circle Arc Layer 1 entered public mainnet operation on September 16, positioned as an economic operating system for the internet. Founding validators include BlackRock, DTCC, ICE, Mastercard, Visa, Standard Chartered, Galaxy, MoneyGram, SBI Group, Sumitomo Corporation and Worldpay, with more than 100 banks, asset managers, payment networks and AI platforms live or onboarding. Arc uses USDC for network fees, supports sub-second finality, EVM compatibility, post-quantum signatures and deterministic consensus, and its testnet processed 700 million transactions.

    Circle has kept stacking AI-native capabilities onto Arc this month: it shipped an Agent Marketplace in late September packaging USDC payment rails and live data tools for developers building autonomous agents, and identity firm Socure brought AI-powered identity checks to the chain, tackling the awkward question of how to verify a counterparty that is software rather than a person. In a weekend conversation with a16z crypto founder Chris Dixon, Allaire said plainly that AI agents will be the main users of Arc, imagining new types of credit where people and machines sit on both the supply and demand sides of money, in marketplaces that resemble a search-advertising exchange more than a bond sale.

    Early experiments hint at the shape: AI agents on Arc hired humans to capture 3D scans of physical spaces and paid them in USDC, forming an economic loop of machines contracting labor and humans cashing out. Arc also plans privacy, high-volume payments and agents sectors, with the payments sector targeting 100,000+ TPS. Allaire expects the stablecoin market to be winner-take-most, leaving room for several networks as it grows from hundreds of billions toward trillions.

    5. The Settlement-Layer Race for Machine Payments Is Officially On

    Seen together, the US is building a full settlement stack for the machine economy that spans the protocol layer and the institutional layer. x402 V2 unifies the payment format at the protocol layer with one-format cross-chain and fiat compatibility, letting Coinbase turn HTTP 402 from theory into the default machine-to-machine handshake; USDC becomes the preferred settlement asset for agent payments, with Token Terminal data showing it leads 30-day agent payment volume on Base and other networks; Arc handles the scaled machine-hires-machine scenario at the institutional layer with compliant validators and sub-second finality. The three map to discoverability, settleability and trustworthiness of machine payments.

    On the supply side, the same narrative is taking shape: Tether backing AIsa, Socure joining Arc identity, Cloudflare opening agent wallets. Stablecoin issuers, infrastructure providers and cloud vendors are all laying guardrails for machine payments. As machine payments move from experiments to infrastructure, the competitive focus has shifted from which protocol can handle micropayments to who can provide speed, compliance and accountability at the same time. For practitioners, the things to watch are USDC share in agent payments, the cross-chain adoption speed of x402 V2, and how much real agent traffic actually lands on Arc.

    Key signal: The settlement-layer race for machine payments has moved from narrative to engineering. x402 V2 unifies cross-chain and fiat interfaces, USDC locks in the agent settlement asset position, and Arc provides an institutional settlement chain, so American companies hold the high ground at both the protocol and institutional layers. The next watershed is whether real agent transactions can cross the demo economy and enter enterprise production.
    1
    Counts do not equal scale87% of the 138M x402 transactions are below $0.10, so cumulative value stays limited. But wallet activation time dropping from 73 days to 18 minutes, and same-hour spending rising from 4% to 67%, show agent payments moving from demo to real tasks. Density signals arrive before scale signals.

    2
    The geographic divide of AI nationalismUS wallets carry 88.1% of model inference payments while Chinese wallets hold nine in ten code-audit transactions. The market for machine-purchased intelligence concentrates where it costs money, and the split between open weights and per-request billing directly shapes where agent payments happen.

    3
    Accountability becomes the regulatory focusChainalysis says payments that are too fast, too small and too numerous cannot be a control point, so responsibility must land on whoever deployed and funded the agent. Cloudflare capped wallets and Arc compliant validators are guardrail designs that turn autonomous machine spending into auditable behavior.

    4
    Both ends of the settlement layer are being claimed at onceCoinbase unifies the payment format at the protocol layer, Circle provides a compliant settlement chain at the institutional layer. Stablecoin issuer Tether backs agent-payment infrastructure AIsa, cloud vendor Cloudflare opens agent wallets, and the supply side is laying complete guardrails for machine payments.
  • USDC Dominates AI-Agent Payments as x402 V2 Reaches Banking Rails

    USDC Dominates AI-Agent Payments as x402 V2 Reaches Banking Rails

    USDC Dominates AI-Agent Payments as x402 V2 Reaches Banking Rails

    Chainalysis counts 138M+ x402 settlements on Base in a year, USDC has become the default payment rail for AI agents, and Coinbase and Circle are pushing machine payments onto cross-chain and institutional settlement layers at the same time.

    x402 annual transactions
    138M+
    On Base network

    USDC circulating supply
    $70-80B
    14-16x the MiCA threshold

    AI inference payments from US
    88.1%
    Wallet geolocation

    Median time to first agent payment
    73d → 18min
    A one-year transformation

    This week the infrastructure battle over machine payments entered a new phase. Chainalysis latest annual report shows AI agents have processed more than 138 million transactions through the x402 protocol on Coinbase Base network in a year, while Token Terminal 30-day data confirms USDC as the stablecoin AI agents use most often for settlement. At the same time, Coinbase released x402 V2 on October 11, using a unified interface to connect Base, Solana and traditional banking networks such as ACH; Circle keeps stacking AI-native capabilities onto Arc, its institutional-grade Layer 1 blockchain, with CEO Jeremy Allaire publicly predicting that AI agents will become Arc primary users.

    Three events look independent but point to the same conclusion: machine payments are switching from a token-issuance narrative to a settlement-rail one, and American companies are seizing the high ground at both the cross-chain protocol layer and the institutional settlement layer.

    1. 138 Million Micropayments: A Density Signal, Not a Scale Signal

    In its 2026 Geography report, Chainalysis counts more than 138 million x402 payments made by AI agents on Base in the 12 months through July 1, 2026. That compares with roughly 1,500 transactions in Q2 2025, a jump of about 90,000x. More than 87% of the payments fall between $0.0001 and $0.10, with the most common range from one to ten cents.

    Micropayments are reshaping the timescales of wallet behavior. At the end of 2025, the median time from a wallet first funding to its first spend was 73 days; by Q3 2026 that had collapsed to 18 minutes. Only 4% of wallets spent within an hour of funding a year ago; that share now stands at 67%, and 89.3% of wallets are reloaded within 30 days of first funding.

    Where the money goes is just as telling: agents buy model inference, tool catalogs, data and research APIs, and code auditing, in other words, robots purchasing AI-generated knowledge on the blockchain. Chainalysis notes that transactions below a dollar make no economic sense for a credit-card network, while a stablecoin that settles for less than a cent fits the scenario naturally.

    Key signal: Surging transaction counts are not a scale signal, they are a density signal. Most of the 138M transactions are cent-level micropayments with limited cumulative value. But wallet activation time dropping from 73 days to 18 minutes, and same-hour spending rising from 4% to 67%, show agent wallets are no longer test demos but working with real tasks.

    2. The US Leads AI Payments: A Geographic Divide of AI Nationalism

    Chainalysis draws a striking split among geolocatable agent payments. US wallets carry 88.1% of AI model inference payments, 41.8% of payments to agent frameworks and tool catalogs, and 23.2% of data and research API purchases, meaning the brain, hands and raw materials of agentic software are paid for mainly from the United States. Chinese wallets account for nine in ten security and code analysis transactions, almost all flowing to AgentLISA, a service that audits Solidity smart contracts with a language model, while also covering 46.7% of financial intelligence and 35% of payment-rail spending.

    Chainalysis explains the split as AI nationalism: DeepSeek and Qwen are free in open weights, while ChatGPT and Claude charge per request, so the market for machine-purchased intelligence concentrates where it costs something. The US ranks first with about 30% of all geolocatable agent-to-service transactions, a number that further confirms the geographic shape of machine payments at the AI infrastructure level.

    Regulatory implications follow. Chainalysis warns that payments that are too fast, too small and too numerous cannot serve as a control point, so responsibility must fall on whoever deployed and funded the agent, not the agent itself. Cloudflare opened capped dedicated wallets for agents in August, while Circle reported USDC circulating supply of $73.3 billion at end of September, up 19% year over year, with $14.8 trillion settled on-chain in a single quarter.

    3. x402 V2: One Format Across Chains, Machine Settlement Straight to Banks

    On October 11, Coinbase released x402 V2 on its developer platform. The core of V1 was reviving the dormant HTTP 402 status code so agents could settle stablecoin micropayments directly over HTTP. The breakthrough of V2 is hybrid compatibility: a unified interface supports both high-performance blockchains such as Base and Solana and traditional banking networks such as ACH and automatic debits, so developers no longer write extra logic for each payment rail.

    The new payTo dynamic-routing feature lets companies set billing rules as intuitively as dragging a web component, and in the future paywalls will no longer stop humans but let machines complete handshakes and checkouts behind each other backs. x402 had already processed more than 100 million transactions in the prior six months; V2 upgrades that into a single payment format that runs cross-chain and is compatible with traditional payment channels. Coinbase works closely with Cloudflare and Circle, using USDC and cryptographic signatures to compress settlement to the millisecond level.

    The move tracks with the x402 Foundation expansion. On September 23, the Foundation merged a spec for exact payments over the Bitcoin Lightning network, with Block contributing the scheme, letting agents pay x402 endpoints in bitcoin via BOLT11 invoices. The x402 rail is extending from a single EVM scope into a general machine-payment protocol covering multiple chains, fiat and bitcoin.

    4. Circle Arc: An AI-Native Design for the Institutional Settlement Layer

    Circle Arc Layer 1 entered public mainnet operation on September 16, positioned as an economic operating system for the internet. Founding validators include BlackRock, DTCC, ICE, Mastercard, Visa, Standard Chartered, Galaxy, MoneyGram, SBI Group, Sumitomo Corporation and Worldpay, with more than 100 banks, asset managers, payment networks and AI platforms live or onboarding. Arc uses USDC for network fees, supports sub-second finality, EVM compatibility, post-quantum signatures and deterministic consensus, and its testnet processed 700 million transactions.

    Circle has kept stacking AI-native capabilities onto Arc this month: it shipped an Agent Marketplace in late September packaging USDC payment rails and live data tools for developers building autonomous agents, and identity firm Socure brought AI-powered identity checks to the chain, tackling the awkward question of how to verify a counterparty that is software rather than a person. In a weekend conversation with a16z crypto founder Chris Dixon, Allaire said plainly that AI agents will be the main users of Arc, imagining new types of credit where people and machines sit on both the supply and demand sides of money, in marketplaces that resemble a search-advertising exchange more than a bond sale.

    Early experiments hint at the shape: AI agents on Arc hired humans to capture 3D scans of physical spaces and paid them in USDC, forming an economic loop of machines contracting labor and humans cashing out. Arc also plans privacy, high-volume payments and agents sectors, with the payments sector targeting 100,000+ TPS. Allaire expects the stablecoin market to be winner-take-most, leaving room for several networks as it grows from hundreds of billions toward trillions.

    5. The Settlement-Layer Race for Machine Payments Is Officially On

    Seen together, the US is building a full settlement stack for the machine economy that spans the protocol layer and the institutional layer. x402 V2 unifies the payment format at the protocol layer with one-format cross-chain and fiat compatibility, letting Coinbase turn HTTP 402 from theory into the default machine-to-machine handshake; USDC becomes the preferred settlement asset for agent payments, with Token Terminal data showing it leads 30-day agent payment volume on Base and other networks; Arc handles the scaled machine-hires-machine scenario at the institutional layer with compliant validators and sub-second finality. The three map to discoverability, settleability and trustworthiness of machine payments.

    On the supply side, the same narrative is taking shape: Tether backing AIsa, Socure joining Arc identity, Cloudflare opening agent wallets. Stablecoin issuers, infrastructure providers and cloud vendors are all laying guardrails for machine payments. As machine payments move from experiments to infrastructure, the competitive focus has shifted from which protocol can handle micropayments to who can provide speed, compliance and accountability at the same time. For practitioners, the things to watch are USDC share in agent payments, the cross-chain adoption speed of x402 V2, and how much real agent traffic actually lands on Arc.

    Key signal: The settlement-layer race for machine payments has moved from narrative to engineering. x402 V2 unifies cross-chain and fiat interfaces, USDC locks in the agent settlement asset position, and Arc provides an institutional settlement chain, so American companies hold the high ground at both the protocol and institutional layers. The next watershed is whether real agent transactions can cross the demo economy and enter enterprise production.
    1
    Counts do not equal scale87% of the 138M x402 transactions are below $0.10, so cumulative value stays limited. But wallet activation time dropping from 73 days to 18 minutes, and same-hour spending rising from 4% to 67%, show agent payments moving from demo to real tasks. Density signals arrive before scale signals.

    2
    The geographic divide of AI nationalismUS wallets carry 88.1% of model inference payments while Chinese wallets hold nine in ten code-audit transactions. The market for machine-purchased intelligence concentrates where it costs money, and the split between open weights and per-request billing directly shapes where agent payments happen.

    3
    Accountability becomes the regulatory focusChainalysis says payments that are too fast, too small and too numerous cannot be a control point, so responsibility must land on whoever deployed and funded the agent. Cloudflare capped wallets and Arc compliant validators are guardrail designs that turn autonomous machine spending into auditable behavior.

    4
    Both ends of the settlement layer are being claimed at onceCoinbase unifies the payment format at the protocol layer, Circle provides a compliant settlement chain at the institutional layer. Stablecoin issuer Tether backs agent-payment infrastructure AIsa, cloud vendor Cloudflare opens agent wallets, and the supply side is laying complete guardrails for machine payments.
  • USDC锁定AI代理支付主导权,x402 V2跨链升级让机器结算直通银行体系

    USDC锁定AI代理支付主导权,x402 V2跨链升级让机器结算直通银行体系

    USDC锁定AI代理支付主导权,x402 V2跨链升级让机器结算直通银行体系

    Chainalysis数据显示x402在Base年度结算超1.38亿笔,USDC成AI代理默认支付轨道,Coinbase与Circle同步把机器支付推向跨链与机构结算层。

    x402年度交易笔数
    1.38亿+
    Base网络

    USDC循环供应
    $700-800亿
    超MiCA门槛14-16倍

    AI推理支付来自美国
    88.1%
    钱包地理定位

    代理钱包首笔支付中位时间
    73天→18分钟
    一年内巨变

    本周,机器支付的基础设施战进入新阶段。Chainalysis最新年度报告显示,AI代理通过x402协议在Coinbase Base网络上的年度交易量已突破1.38亿笔,而USDC被Token Terminal 30天数据确认为AI代理使用最频繁的稳定币结算资产。与此同时,Coinbase在10月11日发布x402 V2,用统一接口打通Base、Solana与ACH等传统银行网络;Circle则持续为机构级Layer 1区块链Arc堆叠AI原生能力,其CEO Jeremy Allaire公开预计AI代理将成为Arc的主要用户。

    三件事看似独立,实则指向同一个结论:机器支付正在从”发币叙事”彻底切换到”结算轨道”,而美国公司正同时抢占跨链协议层与机构结算层两端的制高点。

    一、1.38亿笔微支付:密度信号而非规模信号

    Chainalysis在2026地理报告中统计,到2026年7月1日为止的12个月里,AI代理通过x402在Base完成了超过1.38亿笔支付。这一数字与2025年Q2约1500笔相比增长了约9万倍。其中超过87%的支付金额在0.0001美元至0.10美元之间,最集中的区间是1美分至10美分。

    微支付正在改变钱包行为的时间尺度。2025年底,一个代理钱包从首次入金到首次支出的中位时间为73天;到2026年Q3,这一数字骤降至18分钟。一年前只有4%的钱包会在入金后一小时内消费,现在这一比例达到67%;89.3%的钱包在首次入金后30天内会再次充值。

    这些钱的去向同样耐人寻味:代理购买的是模型推理、工具目录、数据与研究API、代码审计等服务,也就是”机器人向区块链购买AI生成的知识”。Chainalysis明确指出,低于1美元的交易对信用卡网络而言没有经济意义,而能结算低于1美分金额的稳定币天然适配这一场景。

    关键信号:笔数暴涨不等于规模信号,它是密度信号。1.38亿笔中绝大多数是分币级微支付,累计金额依然有限。但钱包激活时间从73天缩短到18分钟、入金后一小时内消费比例从4%升至67%,说明代理钱包不再是测试演示,而是带着真实任务在工作。

    二、美国主导AI支付:AI民族主义的地理分层

    Chainalysis对可地理定位的代理支付做了有趣的划分。美国钱包承担了88.1%的AI模型推理支付、41.8%的代理框架与工具目录支付、23.2%的数据与研究API购买,也就是说,智能体的”大脑、双手与原材料”主要由美国支付。中国钱包则占据九成”安全与代码分析”交易,几乎全部流向AgentLISA这家用语言模型审计Solidity智能合约的服务,同时占据46.7%的金融情报与35%的支付轨消费。

    Chainalysis用”AI民族主义”解释这一分化:DeepSeek与Qwen以开源权重免费提供,而ChatGPT与Claude按请求计费,机器可购买的情报市场因此集中在需要付费的地方。美国以约30%的全球可定位代理服务交易占比居首,这一数字在AI基础设施层面进一步印证了机器支付的地缘格局。

    监管影响也随之而来。Chainalysis提醒,太快、太小、太多的支付无法被当作监管控制点,责任该落到部署与资助该代理的主体身上,而非代理本身。Cloudflare已在8月为代理开设设有额度上限的专用钱包,Circle则报告9月底USDC循环供应达733亿美元,同比增19%,单季链上结算量达14.8万亿美元。

    三、x402 V2:一格式跨链,机器支付直通银行

    10月11日,Coinbase在开发者平台发布x402 V2。V1时代的核心是把沉睡30年的HTTP 402状态码重新激活,让代理通过HTTP协议直接结算稳定币微支付。V2的突破在于”混合兼容”:用统一接口同时支持Base、Solana等高性能区块链与ACH、自动扣款等传统银行网络,开发者无需为不同支付轨道编写额外逻辑。

    新增的”payTo”动态路由功能让企业像拖拽网页组件一样设置计费规则,未来paywall不再拦截人类,而是让机器在彼此背后完成握手与结算。x402此前六个月内已处理超1亿笔交易,V2在此基础上升级为可跨链运行、兼容传统支付通道的单一支付格式。Coinbase与Cloudflare、Circle深度合作,用USDC与密码学签名技术将结算时间压缩至毫秒级。

    这一动作与x402基金会的扩张同步。9月23日,基金会合并了比特币闪电网络上的精确支付规范,Block贡献了该方案,代理可通过BOLT11发票用比特币支付x402端点。x402的支付轨道正在从单一EVM扩展为覆盖多链、兼容法币与比特币的通用机器支付协议。

    四、Circle Arc:机构结算层的AI原生设计

    Circle的Arc Layer 1于9月16日进入公开主网运营,以”互联网经济操作系统”定位。创始验证者阵容包括BlackRock、DTCC、ICE、Mastercard、Visa、Standard Chartered、Galaxy、MoneyGram、SBI Group、住友商事与Worldpay,超过100家银行、资产管理公司、支付网络与AI平台已上线或接入。Arc使用USDC支付网络费用,支持亚秒级最终性、EVM兼容、后量子签名与确定性共识,测试网期间处理了7亿笔交易。

    Circle在本月持续为Arc堆叠AI原生能力:9月底上线Agent Marketplace,打包USDC支付轨道与实时数据工具,供开发者构建自主代理;身份验证公司Socure将AI驱动的身份检查带到Arc,解决”如何验证一个软件对手方”的问题。Allaire在上周末与a16z crypto创始人Chris Dixon的对话中直言,AI代理将是Arc的主要用户,他设想人与机器同时成为货币供需两端的新型信用市场,形态更像搜索广告交易所而非债券发行。

    早期实验已出现雏形:AI代理在Arc上雇用人类采集3D空间扫描并支付USDC,出现”机器雇佣人力、人类套现”的经济循环。Arc还规划了隐私、高并发支付与代理三个板块,其中支付板块目标10万+TPS。Allaire预计稳定币市场将”赢家通吃大部分”,随着市场从数千亿美元走向数万亿,会容纳多条网络共存。

    五、机器支付的结算层竞争正式开局

    把三件事放在一起看,美国正在为机器经济搭建一条贯通协议层与机构层的完整结算栈。x402 V2在协议层把支付格式统一为”一格式跨链、兼容法币”,Coinbase借此把HTTP 402从理论变成机器间默认握手;USDC在资产层成为代理支付的首选结算单位,Token Terminal数据显示其在Base等网络的30天代理支付量居首;Arc在机构层用合规验证者与亚秒级最终性承接”机器雇佣机器”的规模化场景。三者分别对应机器支付的可发现性、可结算性与可信度。

    而Tether投资AIsa、Socure接入Arc身份验证、Cloudflare开设代理钱包,则构成同一叙事的供给侧:稳定币发行方、基础设施商与云厂商都在为机器支付铺设护栏。机器支付从实验走向基础设施,其竞争焦点已从”哪个协议能处理微支付”转向”谁能同时提供速度、合规与责任归属”。对从业者而言,关注点应放在USDC在代理支付中的份额变化、x402 V2的跨链采用速度以及Arc上真实代理交易的落地情况。

    关键信号:机器支付的结算层竞争已从叙事走向工程。x402 V2统一跨链与法币接口、USDC锁定代理结算资产地位、Arc提供机构级结算链,美国公司在协议层与机构层同时占据制高点。下一步的分水岭是真实代理交易能否跨越演示经济,进入企业级生产环境。
    1
    笔数不等于规模1.38亿笔x402交易中87%低于0.1美元,累计金额有限。但钱包激活时间从73天缩短至18分钟、入金一小时消费比例从4%升至67%,证明代理支付正从演示走向真实任务。密度信号先于规模信号出现。

    2
    AI民族主义的地缘分层美国钱包承担88.1%的模型推理支付,中国钱包占据九成代码审计交易。机器购买的情报市场集中在需要付费的地方,开源权重与按请求计费的分野直接塑造了代理支付的地理分布。

    3
    责任归属成为监管焦点Chainalysis明确表示太快、太小、太多的支付无法被当作监管控制点,责任该落到部署与资助代理的主体。Cloudflare的额度钱包、Arc的合规验证者,都是把”机器自主花钱”转化为可审计行为的护栏设计。

    4
    结算层两端同时抢位Coinbase在协议层统一支付格式,Circle在机构层提供合规结算链。稳定币发行方Tether投资代理支付基础设施AIsa,云厂商Cloudflare开设代理钱包,供给侧正为机器支付铺设完整护栏。

  • Listing a Stablecoin Is Now Criminal Exposure: The Traps Hidden in Treasury GENIUS Rule

    Listing a Stablecoin Is Now Criminal Exposure: The Traps Hidden in Treasury GENIUS Rule

    Listing a Stablecoin Is Now Criminal Exposure: The Traps Hidden in Treasury’s GENIUS Rule

    On October 19, the comment period for Treasury’s Section 3 of the GENIUS Act closed with 105 filings. Buried inside was a provision most exchanges overlooked: listing a new stablecoin now carries a potential $1 million fine and five years in prison.

    Key Takeaways

    On October 19, the comment period for the U.S. Treasury’s Section 3 NPRM under the GENIUS Act (91 FR 53368) formally closed, with more than 105 industry comments flooding the docket. What looks like routine rule feedback actually hides several provisions buried in the preamble that are reshaping stablecoin competition. Participation liability turns “listing a new stablecoin” into criminal exposure, the foreign-issuer comparability vacuum exposes DASPs to $100,000-a-day civil penalties starting January 18 2027, and the yield-prohibition boundary dispute (ABA claims 25.9% of deposits would flee) remains unresolved. Meanwhile, an SEC official previewed securities perpetual futures launching this quarter. The U.S. regulatory “compliance stack” is locking into place at the January 18 2027 inflection point.

    Participation Liability: The “Exchange Trap” Buried in the Preamble

    In the GENIUS Act Section 3 implementing rule published on August 18 (TREAS-DO-2026-0496, 24 pages in the Federal Register), Treasury used one sentence to define what constitutes “issuing a payment stablecoin in the United States.” Most market participants focused on the issuance-side reserve and redemption requirements, but the detail worth worrying about sits in the preamble rather than the operative provisions, namely proposed §1523.2(d)(3).

    The provision states that anyone who “knowingly participates” in an unlicensed stablecoin issuance by acting as a market maker for newly issued payment stablecoins, distributing them, or otherwise making them available for secondary trading commits a violation. Section 3(f) of the GENIUS Act sets the consequence: up to $1 million per violation, five years in prison, or both. Treasury explicitly says these examples are “not intended to be exhaustive,” meaning other conduct falls within reach as well. And the key definition, “newly issued,” appears nowhere else in the entire rule and is never defined. Whether an exchange that lists a stablecoin six months after launch triggers liability is a question the rule text does not answer.

    “A person knowingly participates in an unlicensed stablecoin issuance by acting as a market maker for newly issued payment stablecoins, distributing them, or otherwise making them available for secondary trading.”
    — Proposed § 1523.2(d)(3), Treasury GENIUS Act Section 3 NPRM, Federal Register 91 FR 53368

    Treasury’s only softening language says it “generally does not intend” to extend liability to individuals who buy small amounts for their own use, but that carve-out applies only to buyers, not platforms. More subtle is the timeline mismatch: the ban on unlicensed issuance and participation liability are both expected to take effect on January 18 2027, while the DASP prohibition on offering or selling unlicensed stablecoins to U.S. persons does not begin until July 18 2028. As a result, a foreign-issued stablecoin can still be lawfully sold to U.S. customers through mid-2028, yet an exchange can face direct criminal exposure for “listing” it starting January 2027, an 18-month window of genuine compliance uncertainty in between. The proposed rule leaves Question 43 open: can one participant rely on another party’s declaration of lawful issuance? Does reliance on an intermediary’s due diligence provide a defense? The rule does not answer.

    Market data reveals the competitive meaning of this provision. As of June, global stablecoin supply stood at roughly $316 billion (DefiLlama), with USDT at about 59% and USDC at about 24%, together controlling 83% of the market. Supply grew by $102 billion in 2025 and $75 billion in 2024, and the market is now about twelve times its end-2020 size. A rule that penalizes platforms for listing new entrants naturally protects the incumbent duopoly. With institutions like Visa announcing billion-dollar commitments to stablecoin infrastructure, new issuers cannot get listed without risking criminal liability, and Treasury’s “generally does not intend” language offers no binding protection.

    The Foreign Issuer Compliance Vacuum: The Road to January 18 2027

    By the time the comment period closed, Treasury had not determined any foreign regulatory regime to be “comparable” under Section 18 of the GENIUS Act, neither the EU’s MiCA, the UK’s FSMA, nor Singapore’s MAS has been recognized, and no Section 18(b) comparability NPRM has been issued. For cross-border issuers and DASPs, this means the boundary of “what constitutes an issuance in the United States” has become so fuzzy as to be nearly unworkable.

    The consequences are concrete: after January 18 2027, non-compliance triggers civil penalties of $100,000 per day, and Section 3(f) simultaneously exposes violators to criminal liability of up to $1 million per violation and five years in prison. Treasury even makes explicit the extraterritorial reach of Section 3, so long as conduct involves offering or selling a payment stablecoin to a person located in the United States, it falls within jurisdiction even if the issuer sits offshore. How a foreign stablecoin such as Tether’s USDT (whose issuer is a non-U.S. entity) obtains a compliant pathway on U.S. platforms remains entirely unresolved.

    The boundary of the yield prohibition is the other fault line tearing the industry apart. The NPRM itself does not directly implement the Section 4(a)(11) yield ban, which belongs to the OCC, but banks and crypto-native firms are clashing fiercely over how Treasury should interpret the scope of these rewards. The ABA and BPI argue for a broad reading that captures rewards generated by affiliates, exchanges, or third-party platforms. The ABA projects that the proposed rules will trigger a 25.9% reduction in deposits and roughly $1.5 trillion in lost lending capacity, an estimate directly challenged by conflicting research from the Federal Reserve. Coinbase, Circle, and the Chamber of Digital Commerce, by contrast, insist that Congress deliberately limited the prohibition to payments made by the issuer. Both sides are dissatisfied with the OCC’s proposed rebuttable presumption, viewing it as insufficient to resolve the underlying conflict.

    Provision Content Effective Date
    §1523.2(d)(3) Participation Liability Market making, distributing, or listing “newly issued” stablecoins = knowing participation 2027-01-18
    §3(b) Offer/Sale Ban DASPs may not offer unauthorized stablecoins to U.S. persons 2028-07-18
    §3(f) Penalties Civil $100K/day; criminal up to $1M + 5 years 2027-01-18
    §18 Comparability MiCA/FSMA/MAS unrecognized; no 18(b) NPRM TBD
    §4(a)(11) Yield Ban OCC territory; boundary dispute unresolved (ABA vs crypto) TBD

    Running parallel to the Treasury comment close is the SEC: the comment period for Regulation Crypto Assets (S7-2026-27) closes on October 20. Forkast calls the two rules together the “GENIUS compliance stack,” in which the SEC, through its definitional taxonomy (the March 17 SEC/CFTC joint interpretation dividing crypto assets into digital commodities, digital collectibles, digital tools, stablecoins, and digital securities), excludes payment stablecoins from the definition of a security, making the entire January 2027 framework operable. Payment stablecoins are neither securities nor commodities and are governed solely by the GENIUS Act regime. After the CLARITY Act’s September 15 failure (49:50), the administrative path is the only engine moving forward, and these two deadlines are the industry’s last low-cost lever before the rules are finalized.

    The Parallel Track: Securities Perpetual Futures Launch This Quarter

    As stablecoin rules tightened, Jamie Selway, Director of the SEC’s Division of Trading and Markets, delivered a clear timeline at the Security Traders Association market structure conference on October 14: five CFTC-registered DCMs, namely Coinbase, Kalshi, Bitnomial, NADEX, and ICE Futures, filed Form 1-N registration notices in September, and he expects at least four to begin trading perpetual futures on securities this quarter.

    This is a parallel line worth pausing on. Traditional security futures contracts, such as CME’s cash-settled single-stock futures launched on July 27, have expiration dates; perpetual futures have no expiry and instead anchor to the spot price through a funding-rate mechanism: when longs must pay, they pay shorts, and vice versa. This is a contract form born in crypto markets, now entering regulated U.S. equity derivatives. Selway made clear that the SEC’s job is not to judge commercial success but to ensure regulatory standards and foster competition: “Our job is not to judge the potential commercial success or failure of these projects. Instead, we are committed to ensuring they meet our standards and fostering healthy competition that protects and benefits investors to the greatest extent possible.”

    “I expect at least four to begin to trade perpetual futures on securities.”
    — Jamie Selway, SEC Division of Trading and Markets Director, STA Market Structure Conference, Oct 14 2026

    The same day, Coinbase and Deribit launched six U.S. equity perpetual futures on offshore markets: CRWV, ORCL, SOXS, DELL, PLTR, and SNXX, covering individual stocks and ETF-linked underlyings (SOXS tracks the Direxion Semiconductor Bear 3X ETF), all cash-settled in USDC, with leverage up to 50x on some products, and restricted to non-U.S. users. Coinbase acquired Deribit in August 2025 for approximately $2.9 billion and completed integration in early October. The contrast between these offshore products and the regulated U.S. launches is stark: the same contract form, one side settled in USDC at 50x leverage with no U.S. investors, the other going through Form 1-N registration under dual SEC and CFTC oversight. Selway also expects U.S. equity markets to move to 23×5 trading soon, with 24×7 to follow, and the Division is reviewing Regulation NMS Rules 610 and 612 by year-end, fully converging with CFTC Chairman Selig’s push for 24/7 tokenized trading.

    Implications for Practitioners

    1
    Run a “participation liability” stress test before listing any new stablecoin
    The examples listed in §1523.2(d)(3) are not exhaustive, and neither “newly issued” nor “initial listing” is defined. When evaluating a new stablecoin listing, exchanges should build a documented compliance assessment record: issuer license verification, issuance timing, temporal proximity to issuance, and whether market making or distribution is involved. The 18-month liability window (January 2027 vs July 2028) means vague standards will operate in practice, so treat every listing as a decision that can trigger criminal exposure.

    2
    The foreign-issuer “comparability vacuum” is the biggest compliance unknown
    MiCA, FSMA, and MAS have not been recognized as comparable regimes, and no 18(b) NPRM exists. DASPs relying on foreign stablecoins, including USDT, should build a dual-track plan before January 18 2027: one that works in a world where a comparability finding arrives, and one where it does not. For issuers, submitting comparability evidence to Treasury early is more realistic than waiting for a passive conclusion.

    3
    The yield-prohibition boundary dispute will decide stablecoin business models
    ABA and BPI argue for a broad reading (banning rewards from affiliates, exchanges, and third parties), while crypto-native firms insist the ban covers only issuer payments, and both are unhappy with the OCC’s rebuttable presumption. Behind the 25.9% deposit-loss estimate versus the Fed’s conflicting research lies a life-or-death question: whether stablecoins can remain yield-bearing products. Issuers should design yield structures that can be split, keeping issuer-side returns and platform-side incentives separate, to fit whichever interpretation prevails.

    4
    Securities perpetual futures will reshape the derivatives landscape
    At least four DCMs are launching securities perpetual futures this quarter, and the offshore market (Coinbase/Deribit, USDC-settled, 50x leverage) is already ahead. For RWA and tokenized-securities practitioners, the “no expiry plus funding rate” contract form is entering regulated markets, and the Reg NMS 610/612 review could further open DeFi-style trading structures. Assess early whether product and compliance teams can handle this new form.

    5
    January 18 2027 is a “compliance stack” node, not a single-rule node
    Treasury Sec 3 (closed today), SEC Reg CA (closes tomorrow), the OCC GENIUS rules (final version in November), and the SCRC state certification (comments due November 30) all interlock on the same timeline. After CLARITY’s failure, the administrative path is the only engine, and the final shape of these rules depends entirely on the comment records filed today and tomorrow. The industry should plan around January 18 2027 as one holistic switchover date rather than responding rule by rule.

  • 上架即担责:GENIUS 稳定币规则在评论截止日埋下的合规陷阱

    上架即担责:GENIUS 稳定币规则在评论截止日埋下的合规陷阱

    上架即担责:GENIUS 稳定币规则在评论截止日埋下的合规陷阱

    10 月 19 日,财政部 GENIUS 法案第 3 条评论期关闭,105 份评论里埋着一条被多数交易所忽略的条款:上架一枚新稳定币,直接对应最高 100 万美元罚款与五年刑期。

    文章解读

    10 月 19 日,美国财政部 GENIUS 法案第 3 条 NPRM(91 FR 53368)评论期正式关闭,超过 105 份行业评论涌入案卷。表面看这是一次例行的规则反馈,实则几条被埋进序言的条款正在重塑稳定币的竞争结构:参与责任把”上架新稳定币”变成刑事风险敞口,外国发行人可比制度真空让 DASP 在 2027 年 1 月 18 日面临每天 10 万美元的民事罚款,而收益禁令的边界之争(ABA 声称将抽走 25.9% 存款)至今没有答案。与此同时,SEC 官员预告证券永续期货本季度上线。美国监管的”合规堆栈”正在 2027 年 1 月 18 日这个节点上同步锁死。

    参与责任:埋在序言里的”交易所陷阱”

    财政部在 8 月 18 日发布的 GENIUS 法案第 3 条实施规则(TREAS-DO-2026-0496,共 24 页联邦公报)中,用一句话定义了什么构成”在美国发行支付稳定币”。绝大多数市场参与者盯着的是发行端的储备与赎回要求,但真正值得警惕的细节藏在序言(preamble)而非正式条款里,即拟议的 §1523.2(d)(3)。

    该条款规定:任何人”知情参与”未授权稳定币的发行,包括为**新发行**的支付稳定币担任做市商、分发它们、或使其可用于二级交易,即构成违法。GENIUS 法案第 3(f) 条设定了后果:每次违规最高 100 万美元罚款、五年监禁,或两者并罚。财政部明确表示这些例子”并非穷尽列举”,其他行为同样落入射程。而关键定义”newly issued”(新发行)在整份规则中再未出现,也无任何界定。一枚上线六个月后的稳定币,交易所上架它是否触发责任,规则文本没有给出答案。

    “A person knowingly participates in an unlicensed stablecoin issuance by acting as a market maker for newly issued payment stablecoins, distributing them, or otherwise making them available for secondary trading.”
    — Proposed § 1523.2(d)(3), Treasury GENIUS Act Section 3 NPRM, Federal Register 91 FR 53368

    财政部给出的唯一缓和是:其”通常不打算”将责任扩展至为自己使用而小额购买的个人,但这一豁免仅适用于买家,不适用于平台。更微妙的是时间线错位:未授权发行的禁令与参与责任预计在 2027 年 1 月 18 日同时生效,而对美国人提供或销售未授权稳定币的 DASP 禁令要到 2028 年 7 月 18 日才开始。由此,外国发行的稳定币在 2028 年年中之前仍可合法卖给美国客户,但交易所从 2027 年 1 月起就会因为”上架”它而直接背上刑事责任,中间隔着整整 18 个月的合规不确定窗口。拟议规则将问题 43 悬而未决:一个参与者能否依赖另一方的合法发行声明?依赖中介的尽职调查能否免责?规则没有回答。

    市场数据揭示了这条条款的竞争性含义。截至 6 月,全球稳定币供应约 3160 亿美元(DefiLlama),其中 USDT 占约 59%、USDC 约 24%,两者合计控制 83% 的市场。2025 年稳定币供应增长了 1020 亿美元,2024 年增长 750 亿美元,如今的市场规模约为 2020 年底的 12 倍。一个惩罚平台上架新进入者的规则,天然保护了现有双寡头的位置。若 VISA 等机构已宣布数十亿美元的稳定币基础设施投入,而新发行人却无法在不冒刑事责任风险的前提下被交易所上架,”generally does not intend”的措辞并不能提供任何有约束力的保护。

    外国发行人合规真空:通往 2027 年 1 月 18 日

    到评论期关闭时,财政部尚未依据 GENIUS 法案第 18 条认定任何外国监管制度”可比”,无论是欧盟 MiCA、英国 FSMA 还是新加坡 MAS,都未被承认;也没有发布任何 18(b) 可比性 NPRM。对于跨国发行人和 DASP 而言,这意味着”什么构成在美国发行”的边界模糊到了难以操作的地步。

    后果是具体的:2027 年 1 月 18 日之后,不合规的后果包括每天 10 万美元的民事罚款;第 3(f) 条下同时触发每次最高 100 万美元罚款与五年监禁的刑事风险。财政部在第 3 条中甚至明确其域外效力:只要行为涉及”向位于美国的个人提供或销售支付稳定币”,即使发行主体位于境外也在管辖范围内。外国稳定币(如 Tether 的 USDT,其发行主体非美国实体)在美国平台上如何获得合规路径,如今完全悬而未决。

    收益禁令的边界是另一条撕裂行业的主线。NPRM 本身未直接实施第 4(a)(11) 条收益禁令,那是 OCC 的领地,但银行与加密原住民对财政部应如何解释收益边界展开了激烈交锋。ABA 与 BPI 主张宽口径解释:将关联公司、交易所或第三方平台产生的奖励全部纳入禁令范围。ABA 预测,拟议规则将引发 25.9% 的存款流失与约 1.5 万亿美元信贷能力损失。这一估算被美联储的相反研究直接挑战。而 Coinbase、Circle 与数字商会则坚持国会意图仅限发行人自身支付的收益。双方都对 OCC 提出的”可反驳推定”表示不满,认为它不足以解决底层冲突。

    条款 内容 生效时间
    §1523.2(d)(3) 参与责任 做市、分发、上架”新发行”稳定币即构成知情参与 2027-01-18
    §3(b) 提供/销售禁令 DASP 不得向美国人提供未授权稳定币 2028-07-18
    §3(f) 罚则 民事 10 万美元/天;刑事最高 100 万美元+5 年 2027-01-18
    §18 可比性认定 MiCA/FSMA/MAS 均未获认定,无 18(b) NPRM 未定
    §4(a)(11) 收益禁令 OCC 领地,边界之争未解(ABA vs 加密方) 未定

    与财政部评论期关闭同步的是 SEC:Regulation Crypto Assets(S7-2026-27)评论期于 10 月 20 日截止。Forkast 将这两条规则称为”GENIUS 合规堆栈”,SEC 通过定义分类法(3 月 17 日 SEC/CFTC 联合解释将加密资产分为数字商品、数字收藏品、数字工具、稳定币、数字证券五类)把支付稳定币排除在证券定义之外,从而让整个 2027 年 1 月框架变得可操作。支付稳定币既不是证券也不是商品,由 GENIUS 专属制度监管。CLARITY 法案 9 月 15 日折戟(49:50)后,行政路径成为唯一的推进引擎,而这两个截止日期就是行业在规则最终落地前最后的低成本杠杆。

    同一周的另一条线:证券永续期货本季度上线

    在稳定币规则收紧的同时,SEC 交易与市场部总监 Jamie Selway 10 月 14 日在证券交易商协会(STA)市场结构会议上给出一个明确的时间表:五家 CFTC 注册的 DCM,即 Coinbase、Kalshi、Bitnomial、NADEX 和 ICE Futures,已在 9 月提交 Form 1-N 注册通知,他预计至少四家将在本季度开始交易基于证券的永续期货。

    这是一条值得停下来审视的平行线。传统证券期货合约(如 CME 7 月 27 日上线的现金结算个股期货)设有到期日;永续期货没有到期日,靠资金费率机制锚定现货价格:多头持仓者需要支付费率时向空头付费,反之亦然。这正是一种从加密市场诞生的合约形态,如今要进入受监管的美国股票衍生品领域。Selway 明确表示 SEC 的职责不是判断商业成败,而是确保符合监管标准并推动良性竞争:”我们的职责不是判断这些项目可能的商业成败。相反,我们致力于确保其符合我们的标准,并推动良性竞争,从而最大限度地保护和惠及投资者。”

    “I expect at least four to begin to trade perpetual futures on securities.”
    — Jamie Selway, SEC Division of Trading and Markets Director, STA Market Structure Conference, Oct 14 2026

    同一天,Coinbase 与 Deribit 已在离岸市场上线六个美股永续期货:CRWV、ORCL、SOXS、DELL、PLTR 与 SNXX,覆盖个股与 ETF 挂钩标的(SOXS 跟踪 Direxion 半导体做空三倍 ETF),全部以 USDC 现金结算,部分产品杠杆最高 50 倍,仅限非美国用户。Coinbase 于 2025 年 8 月以约 29 亿美元收购 Deribit,10 月初完成整合。这些离岸产品与即将上线的受监管美国产品之间,形成了一个鲜明的对照:同一个合约形态,一边以 USDC 结算、50 倍杠杆、无美国投资者;另一边走 Form 1-N 注册、受 SEC 与 CFTC 双重监管。Selway 还预期美股将很快进入 23×5 交易,24×7 紧随其后,并在年底前审查 Reg NMS 610/612 条款,这与 CFTC 主席 Selig 推动的 7×24 代币化交易叙事完全合流。

    对从业者的一些启示

    1
    上架新稳定币前先做”参与责任”压力测试
    §1523.2(d)(3) 列出的例子并非穷尽,”newly issued”与”initial listing”均无定义。交易所在评估上架一枚新稳定币时,应建立书面化的合规评估记录:发行人牌照验证、发行时点、与发行的时间关联度、是否涉及做市与分发。18 个月的责任窗口(2027 年 1 月 vs 2028 年 7 月)意味着模糊标准将真实运行,把每一次上架当作会触发刑事敞口的决策来对待。

    2
    外国发行人的”可比性真空”是最大的合规不确定项
    MiCA、FSMA、MAS 至今未被财政部认定为可比制度,也没有 18(b) NPRM。依赖外国稳定币(含 USDT)的 DASP 应在 2027 年 1 月 18 日前建立双轨预案:既能运行在”可比性认定出台”的世界里,也能运行在”认定缺席”的世界里。对发行方而言,尽早向财政部提交可比性认定的证据材料,比等待被动结论更现实。

    3
    收益禁令的边界之争将决定稳定币的商业模型
    ABA 与 BPI 主张宽口径(关联方/交易所/第三方奖励全禁),加密方坚持仅限发行人支付,双方都不满意 OCC 的可反驳推定。25.9% 存款流失 vs 美联储相反研究的数字之争背后,是稳定币能否继续作为收益型产品的生死问题。发行方应把收益结构设计为”可拆分”的:发行人端收益与平台端激励分开设计,以适配任何一种最终解释。

    4
    证券永续期货上线将改写衍生品版图
    本季度至少四家 DCM 上线证券永续期货,离岸市场(Coinbase/Deribit,USDC 结算、50 倍杠杆)已经先行。对 RWA 与代币化证券从业者,”无到期日 + 资金费率”的合约形态正式进入受监管市场,Reg NMS 610/612 审查或进一步打开 DeFi 化的交易结构。提前评估产品与合规团队是否具备承接这一形态的能力。

    5
    2027 年 1 月 18 日是一个”合规堆栈”节点,不是单一规则节点
    财政部 Sec 3(今天截止)、SEC Reg CA(明天截止)、OCC GENIUS 规则(11 月最终版)、SCRC 州认证(11 月 30 日评论截止)在同一个时间轴上互相咬合。CLARITY 折戟后行政路径成为唯一引擎,而这些规则的最终形态全部取决于今天与明天这两份评论档案。行业应把 2027 年 1 月 18 日当作一个整体切换日来规划,而非逐条规则应对。